Does Insurance Cover Water Damage at Home?
Does insurance cover water damage? Learn what is usually covered, what is excluded, and what to do first after a leak, burst pipe, or sewer backup today.
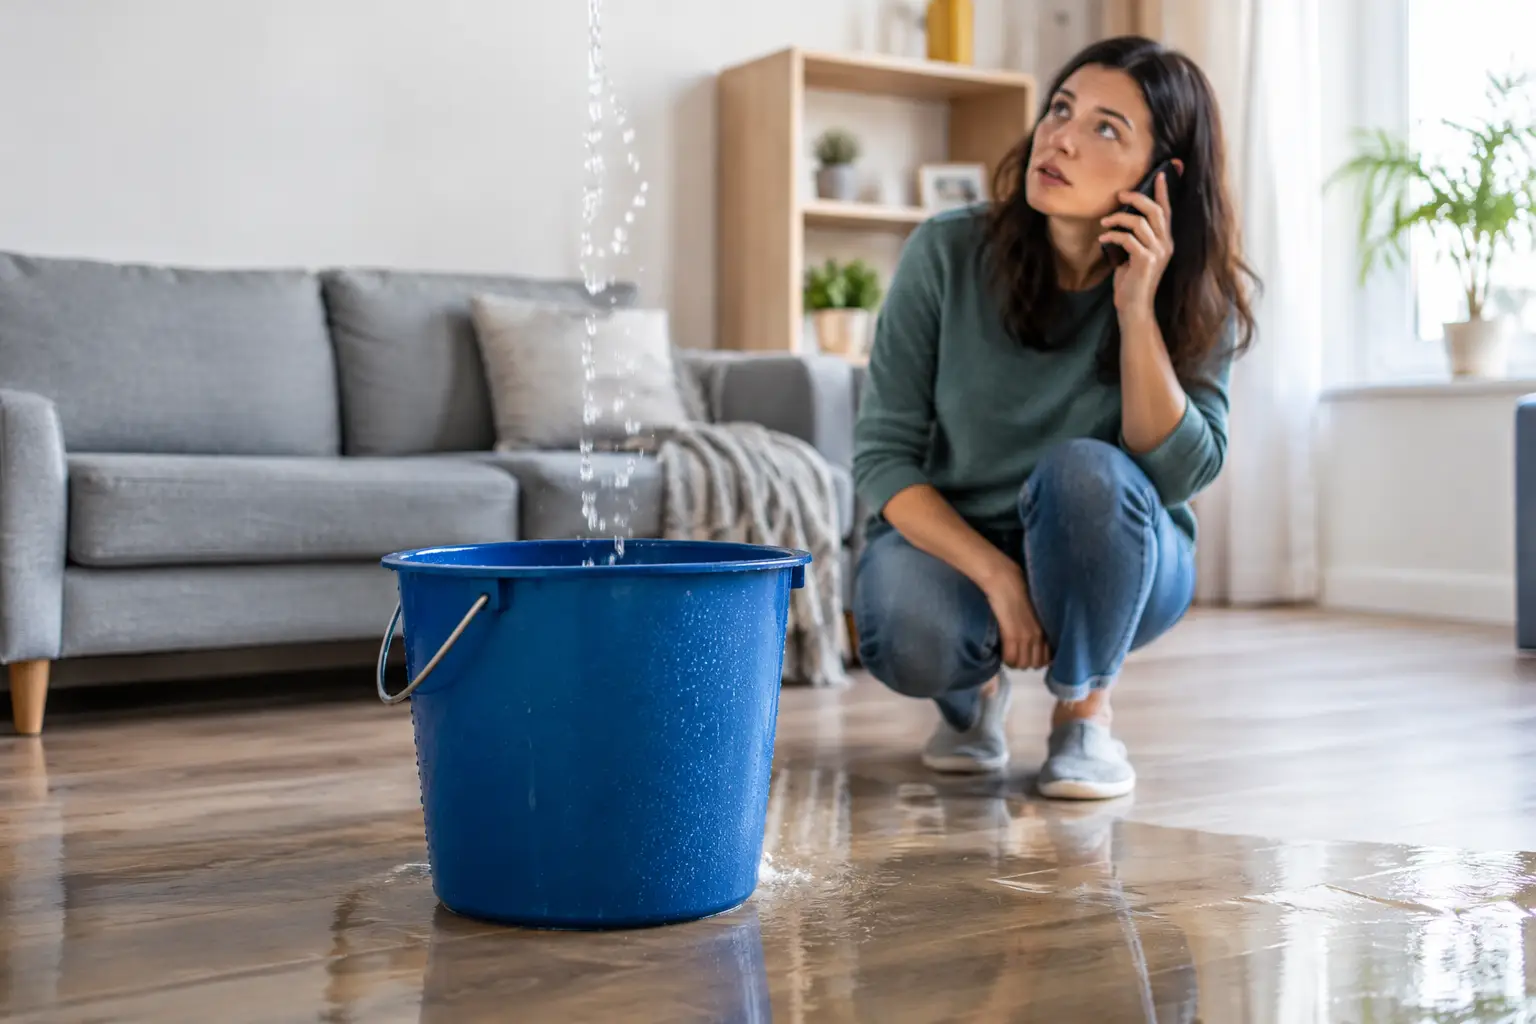
A pipe bursts behind a finished wall, the basement starts taking on water, and the first question is usually: does insurance cover water damage? Often, homeowners insurance can help with sudden and accidental water damage. But the source of the water, the condition of the plumbing, and the coverage on your specific policy all matter.
The practical priority is not figuring out the entire claim while water is still spreading. Shut off the water if you can do so safely, protect people and property, and get the plumbing problem diagnosed and stopped. Then document the damage and contact your insurance carrier.
When does insurance cover water damage?
A standard homeowners policy commonly covers damage caused by a sudden, accidental plumbing failure. A frozen pipe that breaks, a supply line that suddenly fails under a sink, or an unexpected water heater leak may all be covered events. Coverage can include damaged drywall, flooring, insulation, cabinets, and personal belongings, subject to your deductible and policy limits.
The key word is sudden. Insurance is generally designed for unexpected losses, not problems that developed slowly over months or years. If water stains have been spreading beneath a bathroom for a long time or a pipe has been visibly corroding and leaking, the resulting damage may be denied as wear, neglect, or lack of maintenance.
There is also an important distinction between paying for the water damage and paying to replace the failed plumbing part. Your insurer may cover the cost to open a wall and repair the wet drywall after a pipe breaks, but not the old pipe itself if it simply failed due to age. Every policy is different, so ask the adjuster to explain what is covered, what is excluded, and how your deductible applies.
Water damage that is often covered
Homeowners should think about the source before assuming a claim will be approved. These are common situations that may be covered when the failure was sudden and accidental:
- A burst pipe after freezing weather damages a wall, ceiling, or basement.
- A washing machine hose, refrigerator line, or dishwasher supply line suddenly ruptures.
- A water heater fails unexpectedly and releases water onto finished flooring.
- An interior plumbing leak causes immediate, visible damage to cabinets, ceilings, or belongings.
- A plumbing fixture overflows because of a sudden failure, rather than a known recurring problem.
Frozen-pipe claims deserve special attention in the Albany area. Many policies require homeowners to maintain heat in the home or take reasonable steps to protect the plumbing during cold weather. Leaving a vacant home unheated during a hard freeze can create a coverage problem, even if the damage from a burst pipe would otherwise be covered.
A plumber's job is to identify the failure, stop the leak, and document the repair work clearly. An insurance carrier decides coverage. Accurate diagnosis helps you report the event correctly without guessing at what happened.
Water damage that is commonly excluded
Not all water comes from the same place, and insurance policies treat it differently. A standard homeowners policy often excludes or limits damage tied to gradual leaks, groundwater, flooding, and sewer backups.
Gradual damage is one of the most frequent issues. A slow drip beneath a sink can rot a cabinet base and damage flooring before anyone notices. If the leak has been active for a long time, the insurer may view it as a maintenance issue rather than a sudden loss. The same can apply to failed caulking, neglected grout, aging roof leaks, and plumbing components that were clearly deteriorating.
Floodwater is usually not covered by a standard homeowners policy. Water that enters from overflowing rivers, heavy surface runoff, or rising groundwater typically requires separate flood insurance. This distinction matters when a basement is wet after a major storm: water coming through the foundation is handled differently than water released from a broken pipe inside the house.
Sewer and drain backups are another major exception. If a municipal sewer backs up into your basement or a drain overflows, coverage may require a specific water backup endorsement. This is optional coverage on many policies, often with its own limit. It is worth checking before a backup happens, particularly for homes with finished basements or lower-level storage.
The first steps after a leak, burst pipe, or backup
A fast response can limit both damage and disruption. If water is actively flowing, locate the nearest shutoff valve. For a single fixture, that may be the stop valve below the sink or behind the toilet. If the leak cannot be isolated, use the home's main water shutoff.
Do not enter standing water near electrical outlets, appliances, or a breaker panel. If there is any concern about electrical contact, stay clear of the area and contact the appropriate emergency professionals.
Once the water is off, take clear photos and video of the source, wet materials, and affected rooms before major cleanup begins. Save receipts for emergency mitigation, plumbing repairs, and temporary steps taken to prevent further damage. Homeowners are generally expected to take reasonable action to prevent additional loss, but avoid throwing away damaged items until your insurer tells you what documentation it needs.
Next, call a licensed plumbing professional to diagnose and stop the cause. A repair without a clear diagnosis can leave the actual problem in place. A cracked pipe, failed pressure-reducing valve, blocked drain, failed sump pump, or broken supply line each requires a different repair.
Then contact your insurance company or agent to open a claim if the damage appears significant. Give them the facts: when you found the problem, where the water came from, what you did to stop it, and what areas were affected. Do not overstate the cause if it has not been confirmed. The plumbing diagnosis and the insurer's inspection will help establish the details.
What to ask your insurance carrier
You do not need to become an insurance expert during an emergency. You do need clear answers. Ask whether the policy covers the resulting water damage, whether the failed plumbing component is covered, and what deductible will apply.
Also ask about coverage for water extraction, drying equipment, mold-related work, temporary relocation, and damaged personal property. If a sewer backup or sump pump failure is involved, ask specifically whether you have water backup coverage and what its dollar limit is.
Some claims involve more than plumbing repair. A wet wall may need professional drying before it is closed back up. Flooring can require removal, and a finished basement may need mitigation work before reconstruction begins. Getting the leak stopped quickly helps preserve the home and gives the claim process a cleaner starting point.
Preventing the next water damage claim
Most plumbing emergencies cannot be predicted perfectly, but a few maintenance steps reduce the risk. Inspect exposed supply lines under sinks and behind toilets for corrosion, bulging, or moisture. Replace old rubber washing machine hoses with quality braided lines. Know where your main water shutoff is and make sure everyone responsible for the home can operate it.
Before freezing weather arrives, protect vulnerable pipes in unheated areas and address drafts near plumbing. If you leave town during winter, keep the heat on and consider having someone check the home. For basements, test the sump pump and consider a battery backup if groundwater is a recurring concern.
For homeowners in Albany, Colonie, Troy, Delmar, and East Greenbush, the best response to active water damage is simple: stop the water, get the plumbing diagnosed correctly, document what happened, and speak with your insurer before making assumptions about coverage. A fast, code-compliant repair protects the home first. The insurance details can be handled with a clear record of the event and the work completed.